Are you curious about how digital dollars and tokenized versions of real‑world assets can be used for everyday payments? This article explains what stablecoins and tokenized deposits are, how they function, and what you need to know before using them to earn or spend online.
What stablecoins and tokenized deposits actually are
A stablecoin is a type of cryptocurrency designed to keep its price stable relative to a reference asset, most commonly a fiat currency such as the US dollar. Stability is achieved by backing each token with reserves (cash, government bonds, or other assets) or by using algorithmic mechanisms that adjust supply to match demand. Because their value does not swing wildly like Bitcoin or Ethereum, stablecoins are often used for payments, remittances, and as a parking place for crypto earnings.
A tokenized deposit takes the concept a step further. It represents a claim on a traditional bank deposit or other cash‑equivalent asset, but the claim is recorded on a blockchain as a digital token. The token can be transferred instantly, settled on a distributed ledger, and used in decentralized applications (dApps) without the friction of traditional banking processes. Tokenized deposits combine the regulatory safety of a bank‑backed deposit with the programmability of blockchain tokens.
How they work under the hood
For a fiat‑backed stablecoin, the issuing entity holds an equivalent amount of the reference currency in a custodial account. When a user purchases the stablecoin, the issuer transfers the fiat into its reserve and mints the corresponding number of tokens. When the user redeems the token, the issuer burns (destroys) the token and releases the fiat back to the user. Transparency is usually provided through regular audits or attestations that confirm the reserve levels.
Tokenized deposits follow a similar model but are often created by a regulated financial institution that issues a blockchain‑based representation of a deposit account. The institution records the deposit on its balance sheet, while the token on the blockchain reflects the same ownership right. Smart contracts can enforce rules such as interest accrual, transfer limits, or automated compliance checks, making the token usable in DeFi protocols, payment rails, or cross‑border settlements.
Real‑world example
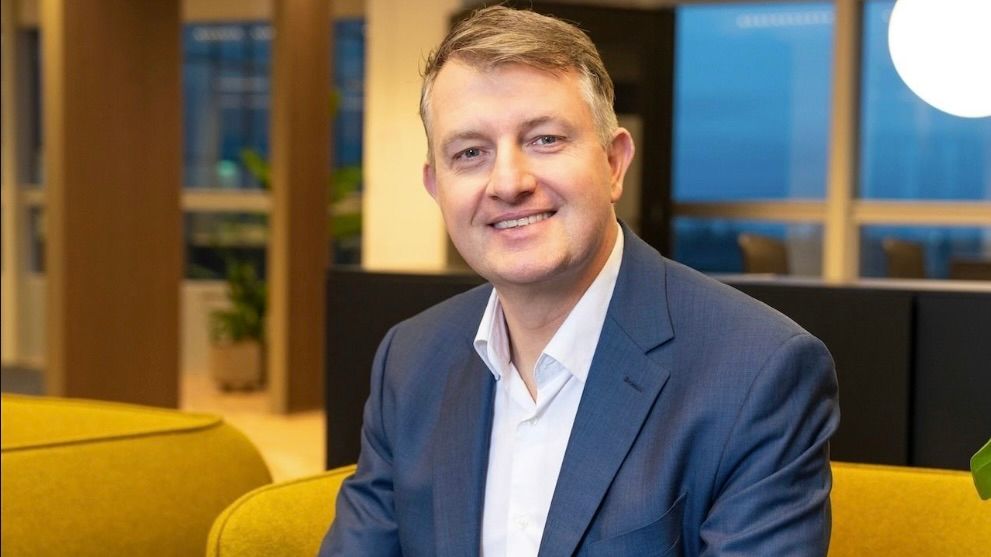
In September 2026, the Solana Foundation announced two senior hires to accelerate its partnerships. One of the new executives, Jamal Raees, said his focus would be “driving greater adoption and usage of stablecoins and tokenized deposits, with an emphasis on global markets.” The announcement followed Solana’s launch of a developer platform that already includes payment infrastructure partners such as Modern Treasury, Mastercard, and Western Union. This move illustrates how blockchain networks are positioning stablecoins and tokenized deposits as core components of modern payment ecosystems.
What it means for you
If you want to earn passive income or make low‑fee payments online, stablecoins can serve as a bridge between traditional finance and crypto. Because their price remains predictable, you can hold them in a wallet, lend them on DeFi platforms, or use them to pay for services that accept crypto. Tokenized deposits add an extra layer of security: they are backed by regulated banks, so the underlying asset is subject to the same protections (such as deposit insurance in some jurisdictions) as a regular bank account.
Both instruments enable faster settlement than traditional bank transfers. Transactions settle in seconds on many blockchains, which can be especially useful for cross‑border payments, recurring subscriptions, or micro‑transactions where conventional banking fees would be prohibitive.
What to check before using them
- Reserve transparency: Look for regular audit reports or attestations that confirm the stablecoin’s backing assets.
- Regulatory compliance: Verify that the issuer is licensed or regulated in the jurisdictions where you operate.
- Network fees and speed: Different blockchains have varying transaction costs and confirmation times; choose one that matches your usage pattern.
- Smart‑contract risk: If you interact with tokenized deposits through DeFi protocols, assess the code audits and the reputation of the platform.
- Custody options: Decide whether you will hold tokens in a non‑custodial wallet (you control the private keys) or a custodial service (the provider holds the keys).
FAQ
Are stablecoins really safe from price swings?
Most fiat‑backed stablecoins maintain a 1:1 peg through reserves, but the safety depends on the issuer’s transparency and the quality of the backing assets. Algorithmic stablecoins without clear reserves can be more volatile.
Can I earn interest on tokenized deposits?
Yes. Some banks and fintech platforms offer interest on tokenized deposits, similar to traditional savings accounts, and DeFi protocols may also provide yield through lending markets.
Do stablecoins count as taxable income?
Holding stablecoins is not a taxable event, but earning interest, receiving rewards, or converting them to fiat can create taxable income. Always consult a tax professional for guidance in your jurisdiction.
What’s the difference between a stablecoin and a tokenized deposit?
A stablecoin is a cryptocurrency that tracks a fiat value, often issued by a private entity. A tokenized deposit is a blockchain representation of a regulated bank deposit, giving it the backing of a traditional financial institution.
This article references reporting from cointelegraph.com.