Ever wondered how central banks can move money across borders instantly without relying on traditional banking corridors? This article explains the mechanics behind cross‑border central bank digital currency (CBDC) platforms, how they differ from other digital assets, and what the implications are for anyone interested in the future of payments.
The plain explanation
A central bank digital currency, or CBDC, is a digital form of a country’s sovereign currency issued and backed by its central bank. Unlike cryptocurrencies such as Bitcoin, a CBDC is a liability of the central bank, meaning it carries the same legal tender status as cash.
When multiple central banks want to settle transactions directly with each other, they can use a shared digital infrastructure known as a cross‑border CBDC platform. The platform typically runs on a permissioned distributed ledger—a type of blockchain where only approved participants (the central banks) can read or write data. Each participating central bank can issue its own digital token that represents its national currency. Those tokens can be transferred on the shared ledger to settle payments, foreign‑exchange trades, or other cross‑border obligations.
Key components of a cross‑border CBDC platform include:
- Shared ledger: A secure database that records every transaction in real time. Because it is permissioned, only the central banks and their designated nodes can validate entries.
- Interoperability protocol: Rules that allow different national digital tokens to be exchanged without needing a third‑party correspondent bank.
- Settlement finality: Once a transaction is recorded, it cannot be reversed, providing certainty for both parties.
- Compliance hooks: Built‑in tools for anti‑money‑laundering (AML) and sanctions screening that satisfy each jurisdiction’s regulatory requirements.
Unlike a single stablecoin that is pegged to a basket of assets, this architecture lets each central bank maintain control over its own monetary policy while still participating in a common network. The result is faster, cheaper, and more transparent cross‑border payments compared with the legacy correspondent‑bank model, which can take days and involve multiple fees.
A real example
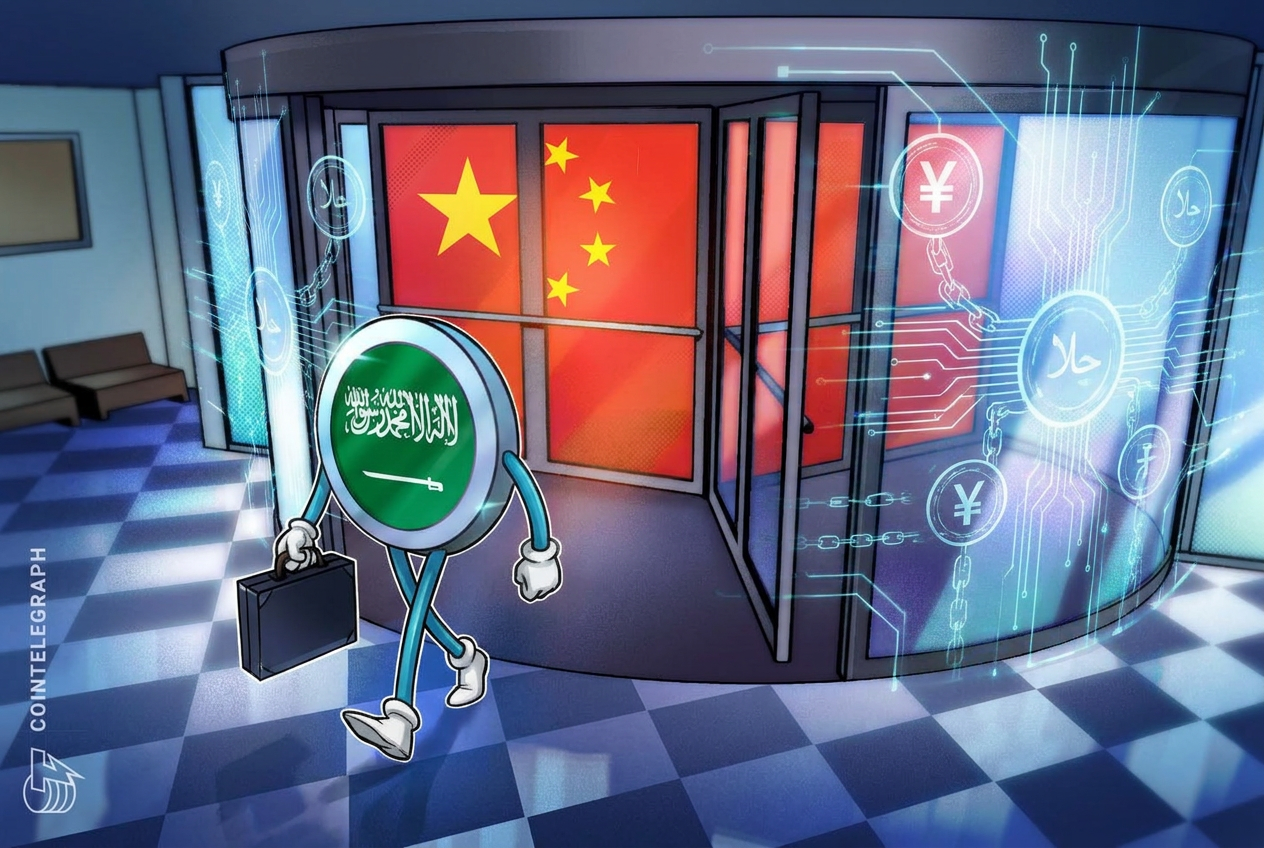
In September 2026, the Saudi Arabian Monetary Authority (SAMA) announced that it had ended its participation in the mBridge project. mBridge was a China‑backed cross‑border CBDC platform launched in 2021 by the Bank for International Settlements (BIS) Innovation Hub together with the central banks of China, Hong Kong, Thailand and the United Arab Emirates. The platform allowed each central bank to issue its own digital currency on a shared ledger for use in cross‑border payments and foreign‑exchange transactions.
SAMA had joined as a full participant in June 2024, completed a proof‑of‑concept trial by May 2025, and then withdrew as planned. The project continued under the BIS until October 2024, when it reached a “minimum viable product” stage and was handed over to the participating central banks. While the United States raised concerns that such networks could help countries evade sanctions, the BIS clarified that its departure was not politically motivated.
What it means for you
For everyday users and businesses, cross‑border CBDC platforms promise several tangible benefits:
- Speed: Payments that once took several days can settle in minutes or seconds.
- Cost reduction: Fewer intermediary banks mean lower transaction fees.
- Transparency: The ledger provides an auditable trail, which can simplify compliance for multinational firms.
- Currency stability: Because each token is backed by a central bank, users avoid the volatility associated with many private stablecoins.
However, these platforms are still in early stages. Participation is limited to a handful of central banks, and the networks are often confined to pilot or proof‑of‑concept phases. Until wider adoption occurs, most consumers will continue to rely on existing payment rails for everyday cross‑border transfers.
What to check / how to judge
If you are evaluating a cross‑border CBDC solution—whether as a business partner, fintech developer, or investor—consider the following criteria:
- Governance model: Identify which central banks are involved and how decisions are made. A clear, multilateral governance structure reduces geopolitical risk.
- Technical standards: Look for adherence to internationally recognized protocols (e.g., ISO 20022, CBDC‑specific standards) that ensure interoperability with other systems.
- Compliance framework: Verify that the platform includes AML, know‑your‑customer (KYC), and sanctions‑screening capabilities that meet the regulations of all participating jurisdictions.
- Stage of development: Distinguish between pilot projects, minimum viable products, and fully launched networks. Early‑stage pilots may have limited functionality and higher uncertainty.
- Risk of political influence: Assess whether the network could be used to circumvent sanctions or other regulatory regimes, as this may affect its long‑term viability.
FAQ
What is the difference between a CBDC and a stablecoin?
A CBDC is issued and backed by a sovereign central bank, giving it the same legal tender status as cash. A stablecoin is typically a private token pegged to an asset (often a fiat currency) and does not carry the same regulatory backing.
Can I use a cross‑border CBDC platform to send money to a friend in another country?
Currently, most platforms are limited to institutional use and pilot testing. Consumer‑focused services may appear in the future, but today you would still rely on banks or existing fintech solutions for personal transfers.
Do cross‑border CBDC networks replace correspondent banks?
They aim to reduce reliance on correspondent banks by allowing direct settlement between central banks. However, full replacement will take time as the networks expand and integrate with existing financial infrastructure.
Is there any risk that my funds could be frozen on a CBDC network?
Because CBDCs are sovereign liabilities, central banks retain the authority to enforce sanctions or freeze assets in line with national law. This is similar to the ability of governments to freeze bank accounts in the traditional system.
This article references reporting from cointelegraph.com.