Do you wonder how a stablecoin like Tether can be used to pay for services, and why government investigators sometimes focus on those transactions? This article explains the mechanics of stablecoin payments, the regulatory landscape that surrounds them, and what the recent Senate inquiry into Tether payments to a political consulting firm illustrates for everyday users.
What a Stablecoin Is and How It Functions as Money
A stablecoin is a type of cryptocurrency designed to maintain a stable value, usually by being pegged to a fiat currency such as the US dollar. The most common model is a fiat‑backed stablecoin, where each token is supposedly backed 1:1 by reserves held in a bank or a trusted custodian. When you buy a stablecoin, you exchange cash for a digital token that can be transferred on a blockchain just like Bitcoin or Ethereum, but its price stays close to $1.
Because stablecoins move on public blockchains, they inherit the speed and low‑cost benefits of crypto. A payment can be sent from one wallet to another in seconds, without needing a traditional bank’s clearing system. The transaction is recorded on the blockchain, giving it transparency and immutability. However, the “backing” – the actual dollars or other assets held in reserve – is managed off‑chain, which means users must trust the issuer’s claims and any audits they provide.
Why Regulators Pay Attention to Stablecoin Payments
Regulators are concerned with three main issues:
- Consumer protection: If the issuer’s reserves are insufficient, users could lose the value of their tokens.
- Anti‑money‑laundering (AML) and sanctions compliance: Stablecoins can be used to move large sums quickly, potentially bypassing traditional banking oversight.
- Securities law: Some stablecoins may be deemed securities if they promise profits or have features that go beyond simple payment.
To address these concerns, agencies such as the Securities and Exchange Commission (SEC) and the Financial Crimes Enforcement Network (FinCEN) have issued guidance on stablecoin issuers, requiring them to register, maintain transparent reserve reports, and implement robust AML programs. In the United States, the Treasury’s Office of Foreign Assets Control (OFAC) also monitors crypto transactions for sanctions violations.
Real‑World Example: Senate Inquiry into Tether Payments
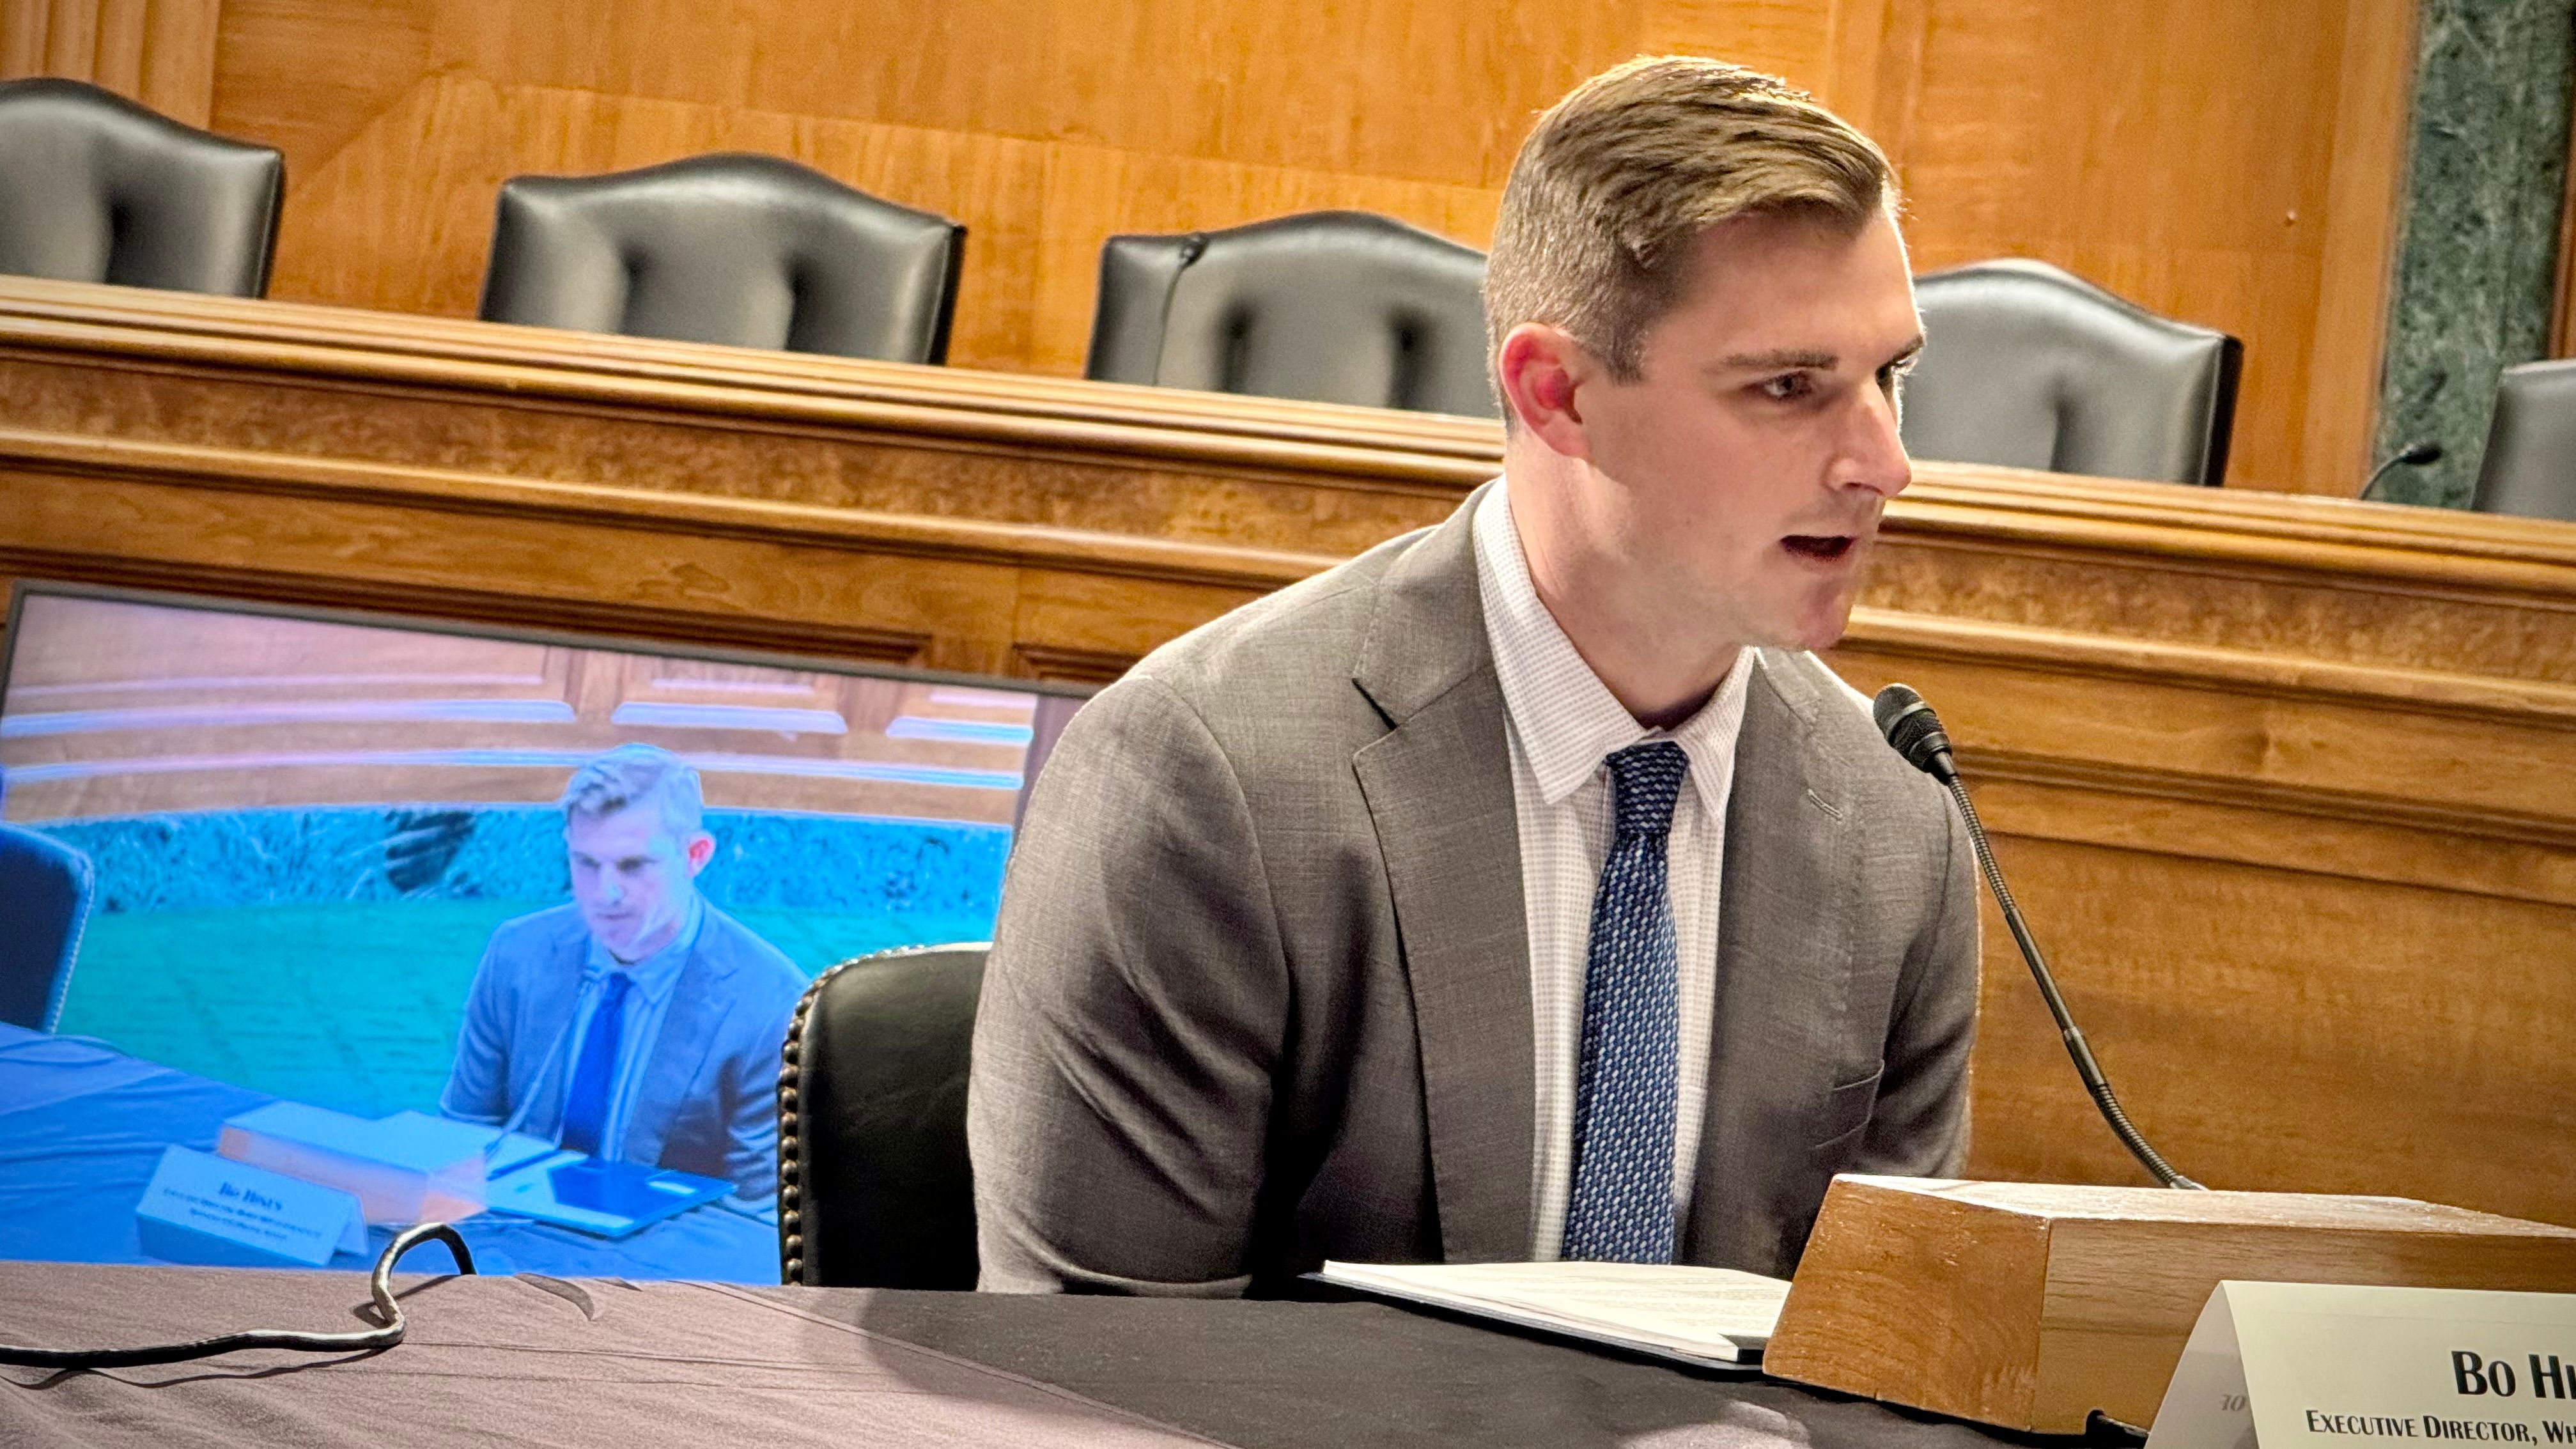
In March 2026, the Senate’s top Democratic investigator announced a probe into payments made in Tether (USDT) to Bo Hines’ consulting firm. The investigation focuses on whether the stablecoin transfers complied with AML rules and whether the funds were properly disclosed under campaign‑finance laws. This case highlights how a seemingly simple stablecoin payment can attract regulatory scrutiny when it involves political consulting, large sums, or cross‑border flows.
What It Means for You
If you use stablecoins to earn passive income, pay for services, or move money across borders, the investigation underscores a few practical points:
- Stablecoin transactions are not invisible; they are recorded on public ledgers that regulators can analyze.
- Choosing an issuer with transparent reserve audits and clear compliance policies reduces the risk of your funds being frozen or questioned.
- When using stablecoins for business or political purposes, you may need to file additional reports or retain documentation to satisfy AML and tax authorities.
How to Evaluate a Stablecoin Before Using It
- Check reserve transparency: Look for regular, third‑party audits that confirm the issuer holds enough assets to back every token in circulation.
- Review regulatory status: Verify whether the issuer is registered with relevant authorities (e.g., SEC, FinCEN) and complies with AML/KYC (Know Your Customer) requirements.
- Assess custody options: Use wallets or platforms that let you control the private keys, or choose reputable custodians that meet security standards.
- Understand fee structure: Stablecoin transfers are cheap, but some issuers charge redemption or withdrawal fees that can affect your net earnings.
- Stay informed about legal developments: Regulations evolve, so keep an eye on guidance from financial regulators and any high‑profile investigations.
FAQ
Are stablecoins really as stable as they claim?
Most fiat‑backed stablecoins aim to maintain a 1:1 peg to a currency, but the stability depends on the issuer’s reserve management and audit practices. If reserves are insufficient, the peg can break.
Do I need to report stablecoin earnings on my taxes?
Yes. In most jurisdictions, stablecoins are treated as property or currency for tax purposes, meaning any gains, losses, or income must be reported.
Can stablecoins be used for illegal activities?
Because they move quickly and can be transferred globally, stablecoins can be misused. That is why regulators enforce AML and sanctions compliance on issuers and users.
Is it safe to keep large amounts of stablecoins in a single wallet?
Holding large sums in a non‑custodial wallet gives you full control but also full responsibility for security. Consider using hardware wallets and diversifying across reputable custodians to mitigate risk.
This article references reporting from coindesk.com.