Wondering how the tax rules apply to your crypto earnings? This article breaks down the basics of cryptocurrency taxation, explains the key concepts you’ll encounter on a tax form, and shows you how to stay compliant while earning online.
What crypto taxes are and how they work
In most jurisdictions, tax authorities treat cryptocurrency as property rather than currency. That means every time you sell, trade, or use a digital asset, you create a taxable event. The profit or loss you realize is calculated by subtracting your cost basis (the amount you originally paid, plus any fees) from the fair market value of the asset at the moment of the transaction.
There are three main types of taxable events:
- Capital gains or losses: When you sell crypto for fiat (like USD) or exchange it for another crypto, the difference between the sale price and your cost basis is a capital gain (taxable) or loss (deductible).
- Income: Receiving crypto as payment for goods, services, or as a staking reward is treated as ordinary income. The amount you report is the fair market value at the time you receive it.
- Hard forks and airdrops: New tokens you receive from a fork or airdrop are generally taxable as income, based on their market value when they become yours.
Tax rates differ for short‑term (held ≤ 1 year) versus long‑term (held > 1 year) capital gains. Short‑term gains are taxed at ordinary income rates, while long‑term gains often enjoy lower rates. The exact percentages depend on your overall taxable income and the tax brackets in your country.
Real‑world illustration
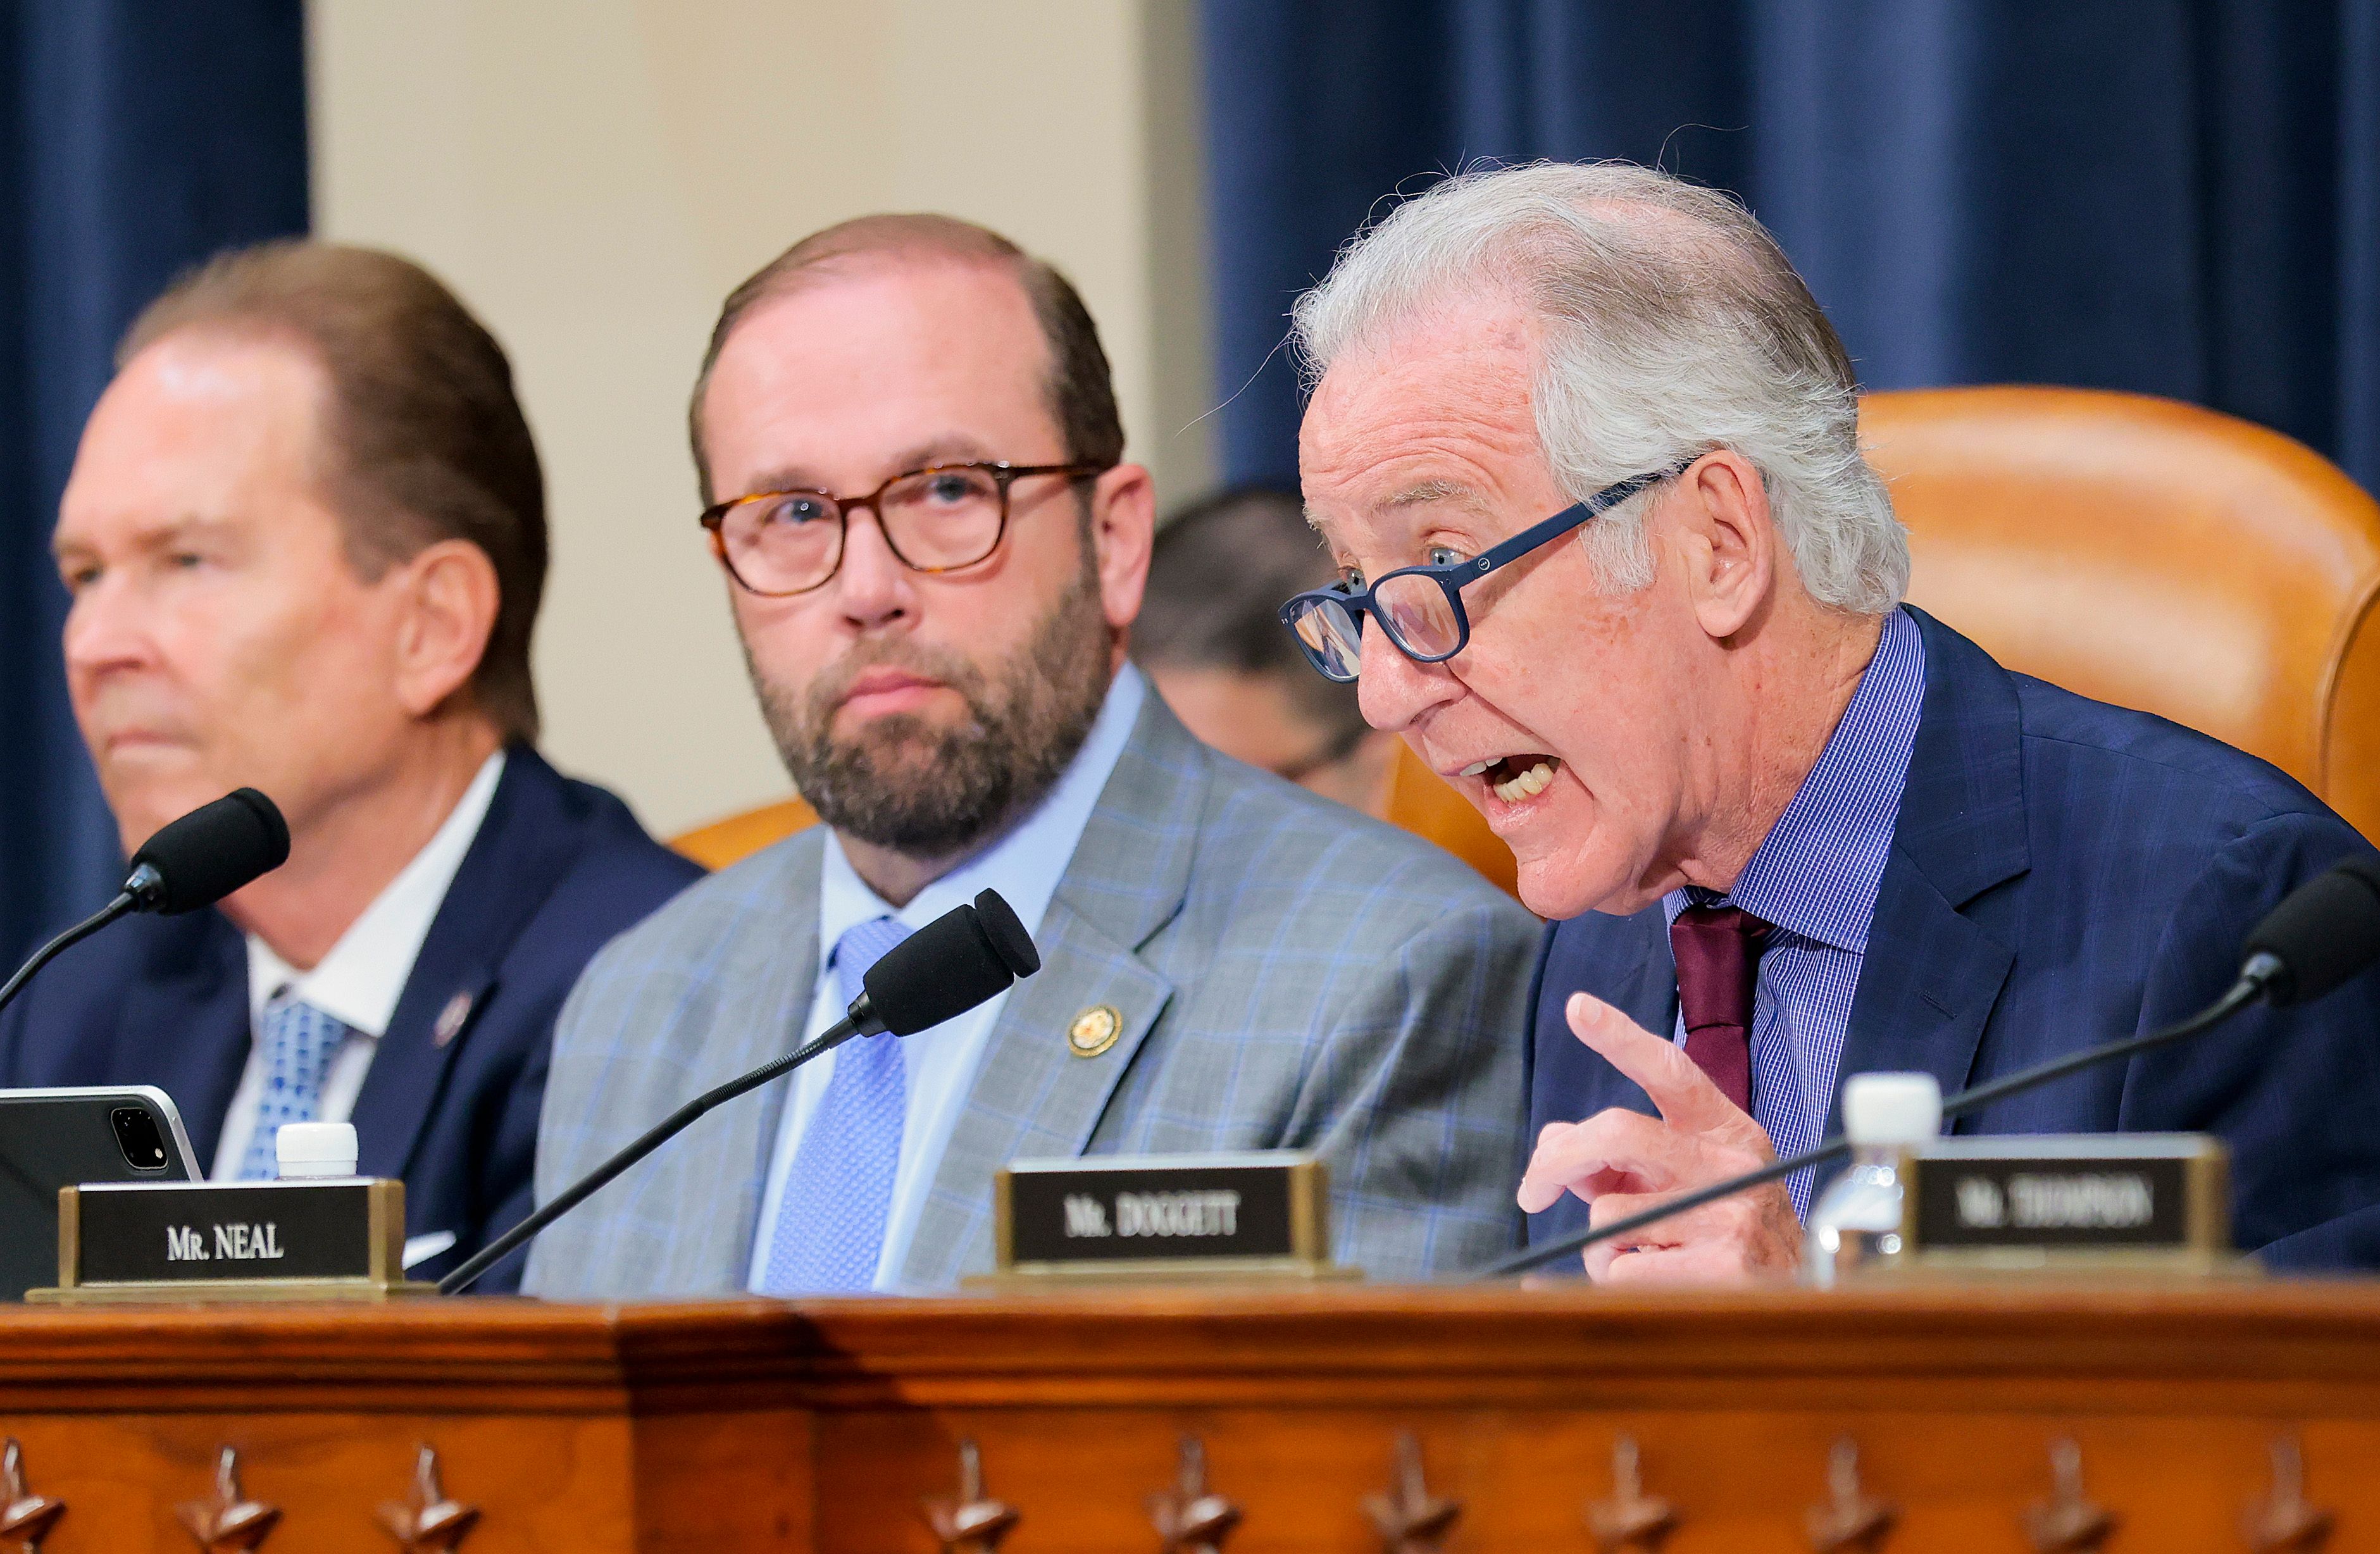
In March 2026, the U.S. House Ways and Means Committee advanced a crypto tax bill following the failure of the earlier “Clarity Act.” The proposal would codify existing guidance that treats crypto as property, clarify reporting thresholds, and introduce a small exemption for low‑value transactions. While the bill’s final language is still pending, it highlights how legislators are shaping the rules that affect every crypto holder.
What it means for you
Whether you earn passive income from staking, trade on an exchange, or receive a payment in Bitcoin, you must keep records of each transaction. Accurate bookkeeping lets you calculate gains, claim legitimate deductions, and avoid penalties. Even small, frequent trades can add up to a significant reporting burden if you don’t track them.
For casual earners, the key takeaways are:
- Every time you move crypto out of a wallet and into another asset, you may have a taxable event.
- Staking rewards count as income at the moment they are credited to your account.
- If you hold an asset for more than a year before selling, you could qualify for the lower long‑term capital‑gain rate.
How to stay compliant – a quick checklist
- Record every transaction: Note the date, amount, type of crypto, fiat value at the time, and any fees.
- Separate income from capital gains: Income includes mining, staking, airdrops, and payments for services. Capital gains arise from disposals.
- Use reliable software: Portfolio trackers can export CSV files that simplify tax calculations.
- Know your thresholds: Some jurisdictions exempt tiny transactions; the 2026 U.S. bill proposes a modest exemption, but you must still report above that limit.
- Consult a tax professional: Crypto tax law is evolving, and a qualified accountant can help you apply the rules correctly.
FAQ
Do I have to report crypto trades that result in a loss?
Yes. Reporting losses can offset other capital gains and reduce your overall tax bill, so it’s beneficial to include them.
Are crypto-to-crypto swaps taxable?
Swapping one cryptocurrency for another is treated as a disposal of the first asset and acquisition of the second, creating a taxable event based on the fair market value at the swap time.
What if I receive a small amount of airdropped tokens?
Even tiny airdrops are considered income when you gain control of the tokens. Some tax authorities allow a de‑minimis exemption, but you must verify the specific threshold in your jurisdiction.
Can I deduct transaction fees?
Yes. Fees paid to exchanges or wallets can be added to your cost basis, reducing the taxable gain.
This article references reporting from coindesk.com.