Do you worry that you might have missed reporting crypto earnings on your tax return? This article explains what a voluntary disclosure is, how the IRS handles it, and what recent changes mean for anyone who wants to clean up past mistakes.
What is a voluntary disclosure?
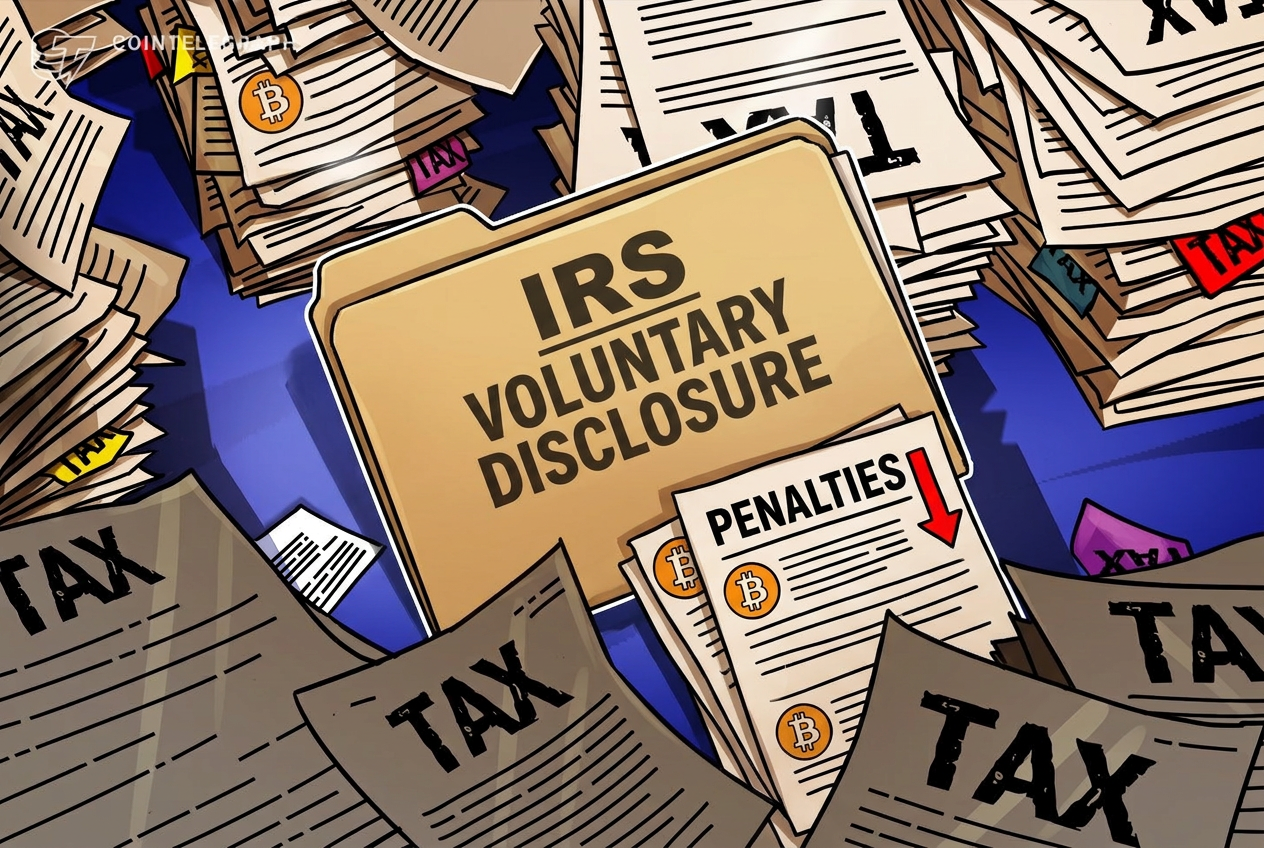
A voluntary disclosure is a formal process that lets taxpayers admit to tax non‑compliance before the tax authority discovers the error. By coming forward on their own, taxpayers can avoid criminal prosecution and often receive reduced penalties. The U.S. Internal Revenue Service (IRS) runs a Voluntary Disclosure Practice (VDP) that applies to all kinds of tax issues, from unreported wages to undeclared cryptocurrency transactions.
The key elements of a voluntary disclosure are:
- Willful vs. non‑willful error: The VDP is designed for “willful” non‑compliance—situations where a taxpayer intentionally avoided reporting. Unintentional mistakes are usually handled through ordinary amended returns, but the line can be blurry, especially with the complex reporting rules for digital assets.
- Submission of a full package: Taxpayers must provide a detailed statement of the alleged violations, all related tax returns, and a calculation of the taxes, interest, and penalties owed.
- Resolution timeline: Historically, the IRS could take a year or more to review a disclosure. The process includes a review of the facts, a determination of penalties, and, if accepted, a settlement agreement.
- Potential outcomes: If the IRS accepts the disclosure, the taxpayer avoids criminal charges and receives a penalty that is typically lower than the maximum statutory amount. The taxpayer also gets a clear path to pay any tax and interest owed.
How the IRS handles crypto in a disclosure
Cryptocurrency is treated as property for U.S. tax purposes. This means every sale, trade, or use of crypto that results in a gain or loss must be reported on Form 8949 and Schedule D. Because many crypto transactions occur on platforms that do not issue 1099‑B forms, taxpayers often miss reporting some activity.
Until now, the IRS has processed crypto cases through the same VDP used for other assets. There has been no separate “digital‑asset” disclosure track, which sometimes left taxpayers unsure whether their crypto errors qualified for the program.
Recent overhaul of the voluntary disclosure program
In October 2026, the IRS announced plans to revamp its voluntary disclosure program. According to statements from IRS Criminal Investigation Chief Jarod Koopman at the UCLA Extension Tax Controversy Conference, the agency intends to launch the revised program before December 2026. The new rules will aim to:
- Reduce the monetary penalties that taxpayers face when they disclose past violations.
- Accelerate case resolution, targeting a 120‑day window from the submission of the required documents.
- Offer flexible payment options, such as installment plans or offers in compromise, to settle outstanding tax liabilities.
Importantly, the overhaul does not create a separate process for digital assets; crypto will continue to be handled under the same VDP framework, but with the same lower‑penalty and faster‑resolution benefits now promised for all taxpayers.
What this means for you
If you have earned crypto through mining, staking, or trading and suspect you have under‑reported, the updated VDP makes it easier and cheaper to correct the mistake. Lower penalties mean you will likely pay a fraction of what you might have owed under the previous regime. Faster case handling reduces the period of uncertainty, allowing you to move on with your financial planning sooner.
The option to settle via installment plans is especially helpful for crypto earners whose cash flow may be tied up in digital assets. Instead of paying a lump sum, you can arrange a schedule that matches your income streams, whether those come from ongoing mining rewards, cloud mining contracts, or periodic token sales.
How to evaluate whether you should use the voluntary disclosure program
- Identify unreported crypto activity: Review wallet addresses, exchange statements, and DeFi platform records for any transactions that generated taxable events.
- Calculate the tax owed: Use a reliable crypto tax calculator or consult a tax professional to determine gains, losses, and the resulting tax liability.
- Assess willfulness: If you knowingly omitted crypto income, the VDP is appropriate. If the omission was accidental, you may simply file an amended return, but the VDP can still provide peace of mind.
- Gather documentation: Compile transaction histories, exchange reports, and any supporting evidence of the amounts involved.
- Consult a tax advisor: A professional familiar with crypto tax law can help you prepare the disclosure package and negotiate payment terms if needed.
FAQ
Will a voluntary disclosure protect me from criminal charges?
Yes. By voluntarily coming forward before the IRS discovers the error, you generally avoid criminal prosecution, provided the disclosure is complete and truthful.
How much lower can the penalties be under the new rules?
The IRS has not published exact numbers, but it has indicated that penalties will be “substantially lower” than the current maximums, which can reach up to 25 % of the tax due for willful violations.
Do I still need to pay interest on the back taxes?
Interest accrues on any unpaid tax from the original due date until the tax is paid in full. The revised program does not eliminate interest; it only reduces the penalty portion.
Can I use the VDP if I only have a small amount of crypto income?
Yes. The program applies regardless of the amount, though for very small discrepancies an amended return may be simpler. The VDP’s lower penalties can still make it worthwhile if you prefer a formal resolution.
This article references reporting from cointelegraph.com.